
Buy a home
Conventional, FHA, VA, jumbo and down-payment assistance, with a pre-approval that has been underwritten before the letter goes out.
Purchase loans
Residential and commercial lending from Signal Hill, California. Every file is read, priced and closed by Troy Ranniker. A licensed California mortgage broker since 2004.
Over the last two weeks the 30-year fixed has been climbing, and a loan fixed for its first five years has been pricing well below it. On the right file that gap is a noticeably lower payment for the years that matter most to you.
It is not for everyone. After five years the rate adjusts, so it fits people who expect to sell, refinance or pay the loan down inside that window. If that is you, it deserves a look before you lock a 30-year out of habit.
I watch the 10-year Treasury every morning because it shows where 30-year mortgage rates are heading. The board below has today's close. If you are comparing a quote from your bank, call me and I will tell you where the market is right now.
Mortgage rates follow the bond market. The 10-year Treasury moves first, so it is the number Troy checks every morning. Check back as often as you like.
Closing yields for . Source: U.S. Department of the Treasury, daily par yield curve. Treasury yields are market indicators, not mortgage rates or an offer to lend.
| Date | 2-yr | 5-yr | 10-yr | 30-yr |
|---|---|---|---|---|
| Nov 17 | 4.80 | 4.90 | 5.10 | 5.46 |
| Nov 16 | 4.83 | 4.93 | 5.12 | 5.46 |
| Nov 13 | 4.88 | 4.98 | 5.15 | 5.47 |
| Nov 12 | 4.86 | 4.95 | 5.10 | 5.43 |
| Nov 10 | 4.73 | 4.81 | 4.98 | 5.35 |
| Nov 9 | 4.56 | 4.67 | 4.88 | 5.26 |
| Nov 6 | 4.51 | 4.64 | 4.86 | 5.26 |
| Nov 5 | 4.46 | 4.59 | 4.84 | 5.25 |
| Nov 4 | 4.58 | 4.69 | 4.90 | 5.28 |
| Nov 3 | 4.61 | 4.74 | 4.95 | 5.32 |
A rate depends on the loan, the property and your file. Troy quotes it himself, in writing, with every cost itemized.
Four ways to start. Each one leads to a program Troy places himself, with the costs explained before you commit to anything.
Conventional, FHA, VA, jumbo and down-payment assistance, with a pre-approval that has been underwritten before the letter goes out.
Purchase loansLower the payment, shorten the term or take cash out, with the before-and-after on the table before you decide.
Refinance optionsHELOCs and fixed-rate second mortgages that leave the first mortgage you already have untouched.
Home-equity solutionsDSCR loans that qualify on the property’s rent, for landlords adding a door or refinancing a rental.
DSCR investor loansAgency loans priced where they belong, and the programs most lenders don’t offer for the files most lenders decline.
Fannie Mae and Freddie Mac financing with agency pricing for documented income, including high-balance for Los Angeles County.
Lower down payments and flexible credit guidelines for purchases and refinances, insured by the Federal Housing Administration.
Zero-down purchase and refinance options for eligible veterans, service members and surviving spouses, with no monthly mortgage insurance.
FeaturedLoan amounts above the county conforming limit for higher-value homes, with underwriting that reads the whole financial picture.
A 30-year loan with the rate fixed for its first five years, often priced below a 30-year fixed. For people who will sell, refinance or pay down inside that window.
FeaturedInvestor financing qualified on the property's rental income rather than personal tax returns.
FeaturedSelf-employed income documented with 12 or 24 months of deposits instead of tax returns.
Apartment buildings of five units or more, mixed-use and owner-occupied commercial property, underwritten on the building's income.
FeaturedA revolving line against your equity that you draw on as you need it, leaving your first mortgage untouched.
A lump sum behind your first mortgage with a fixed rate and a fixed payment for a set term.
Qualify on liquid assets when the income on paper does not tell the story.
CalHFA and local assistance paired with an FHA, VA or conventional first mortgage to cover part of the down payment or closing costs.
A documented history of rent and bills paid on time can stand in for a credit score.
Rural and large-lot properties that standard guidelines turn away, financed with the land counted properly.
All loan programs, including purchase, refinance and debt consolidation
Most mortgage companies hand your file from a salesperson to a processor to an underwriter you’ll never meet. At Ranniker Lending the person who quotes the loan is the person who closes it.
On the first call he tells you whether it works, what it costs and what to send. Nobody is handed off.
California DRE broker license 01403185, issued January 2004. Company NMLS 355886.
Bank-statement, asset-depletion, DSCR, non-traditional credit and high-acreage lending, alongside full agency, FHA and VA.
“Where preciseness is the key to success.” Every figure you receive is dated, sourced and explained in plain language.
If you run a business, your tax returns are written to minimize income, and a bank reads them exactly that way. A bank-statement loan documents what you actually earn: 12 or 24 months of business or personal statements, no tax returns required.
A debt-service-coverage-ratio loan asks one question: does the rent cover the payment? Troy uses it for investors adding a door, refinancing a rental or buying with personal income that is complicated on paper.
Two ways to borrow against the home you already own without touching the first mortgage you already have.
| Feature | HELOC | Fixed second |
|---|---|---|
| Structure | A revolving line of credit you draw on, repay and draw again during the draw period. | A lump sum funded at closing, repaid over a set term. |
| Rate | Typically variable, tied to an index. | Fixed for the life of the loan. |
| Payment | Based on what you have drawn. | The same every month. |
| Often used for | Renovations in phases, a reserve for the unexpected, tuition paid over time. | A single large cost, or consolidating higher-rate debt into one fixed payment. |
| Learn more | HELOC | Fixed second |
About debt consolidation: paying off credit cards or personal loans with a second mortgage turns unsecured debt into debt secured by your home. Troy walks through the total cost and the trade-offs before you decide. Read how it works.
From the first conversation to funding, you deal with Troy. The full process
A short call about the property, the goal and how you earn. He tells you which programs fit before you send a document.
Credit, income and assets reviewed by Troy, then a written pre-approval sized to the offer you want to make.
The appraisal is ordered, conditions are cleared personally and you hear about every milestone from him.
Signing is scheduled around you. Troy coordinates escrow so the loan funds on the contract date.
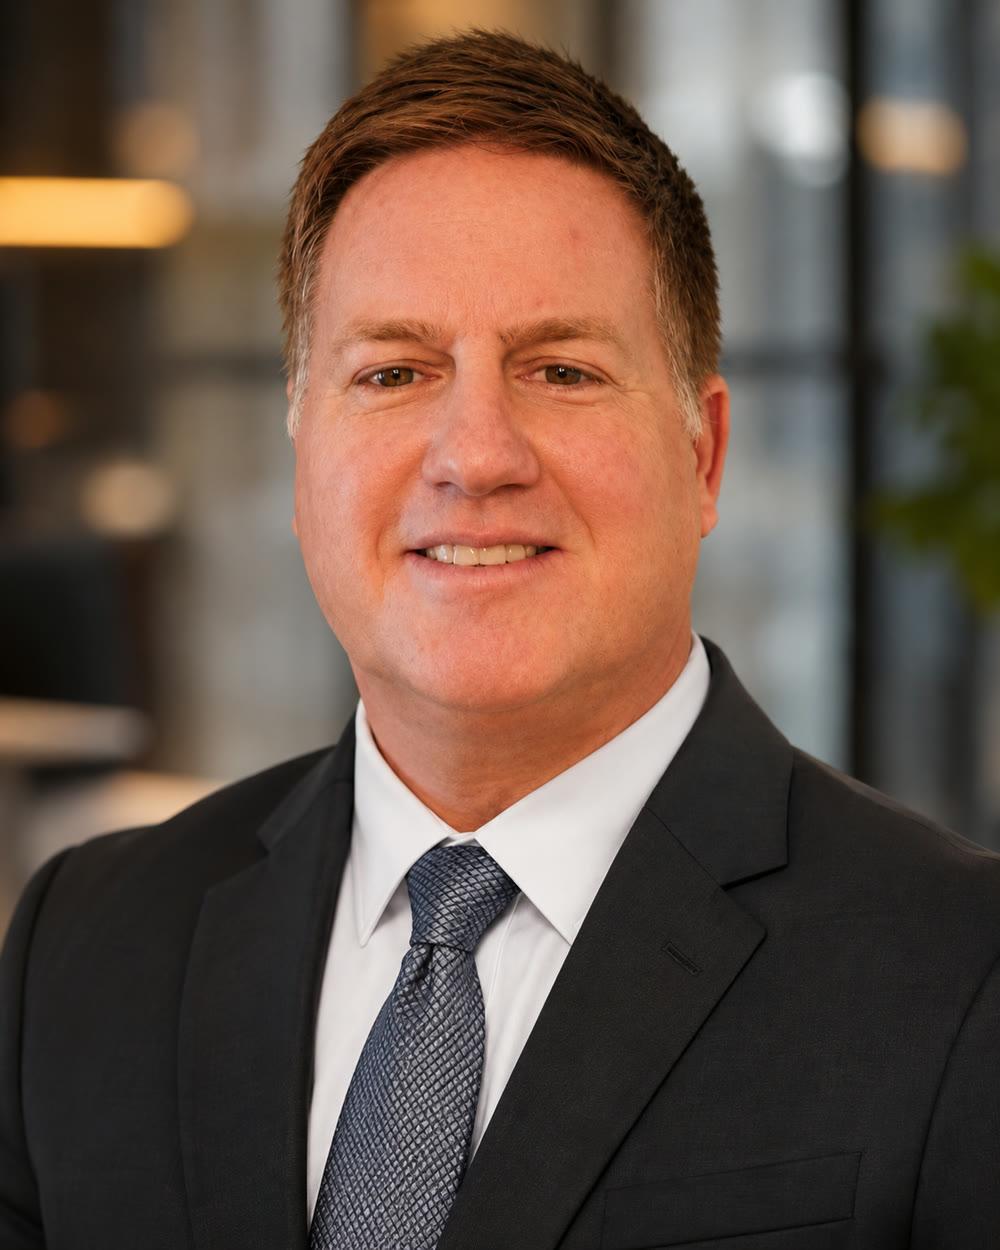
Troy Ranniker has held a California real estate broker license since January 2004 and founded Ranniker Lending in Signal Hill to run a mortgage company one way: the person who quotes your loan is the person who closes it.
He specializes in the files larger lenders decline, from bank-statement and asset-depletion income to DSCR investor loans and high-acreage property, alongside full conventional, FHA, VA and jumbo lending for Southern California buyers and owners.
Off the clock, Troy’s other discipline is general aviation: checklists, precision and a plan for every leg. It shows in how he runs a file.
Plain-language guides to the programs Troy places most, written for Southern California borrowers.
How 12 or 24 months of deposits become qualifying income, what underwriters look for, and the documents to gather first.
What the ratio measures, how rent is counted, and why a strong property can qualify when personal income can't.
Choosing the right way to use your equity, and the questions to answer before consolidating debt into your home.
How county loan limits work, what changes above them, and how jumbo files are underwritten.
A conversation with Troy costs nothing and comes with no obligation. Tell him what you’re trying to do and he’ll tell you what’s possible.