
Commercial lending, from the person who quotes it.
Apartment buildings of five units or more, mixed-use buildings and the property your business operates from. Troy underwrites the building's income himself and puts the terms in writing after the first call.
- Property types
- 5+ unit apartments, mixed-use, owner-occupied commercial
- Underwriting
- Net operating income and sponsor strength
- Pricing
- Quoted in writing after the first call
- Where
- California
How it works
A commercial loan is underwritten differently from a home loan. The lender looks first at the property: what it earns, what it costs to run and whether the income that is left comfortably covers the payment. Then it looks at you, the sponsor: your experience, your liquidity and your other holdings.
Troy places loans on apartment buildings of five units or more, mixed-use buildings with shops below and apartments above, and commercial property occupied by the owner's business. Each has its own lenders and its own rules, and matching the building to the right one is most of the work.
You deal with Troy from the first call to funding. He reads the rent roll and the operating statement himself, tells you what the building supports and puts the terms in writing before you spend money on reports.
- Investors buying or refinancing an apartment building of five or more units
- Owners of mixed-use property
- Business owners buying the building they operate from
- Investors moving up from one-to-four-unit rentals
- Owners with a loan coming due who need a new one in place first
Not sure you fit? Ask. Troy tells people on the first call when a different program serves them better.
What to consider
Program details vary by investor and change over time. These are the questions that decide whether the loan is right for you; Troy confirms the specifics for your file.
Net operating income
The loan is sized on the income left after operating expenses. A clean rent roll and operating statement are worth more than any other document.
Term and amortization
Commercial loans often come due before they are fully paid off. Troy explains the term, the amortization and what is owed at the end.
Prepayment
Many commercial loans charge for early payoff. The structure matters if you may sell or refinance, so it is settled before you choose a lender.
Third-party reports
An appraisal and, depending on the property, environmental and physical reports are ordered at your cost. Troy confirms the loan is viable before any are ordered.
The process
From the first conversation to funding, you deal with Troy.
Talk with Troy
A call about the building, its income and your plan. He tells you which lenders fit before you send a document.
Written terms
Troy reviews the rent roll and operating statement and returns proposed terms in writing.
Underwriting and reports
The appraisal and any required reports are ordered and conditions are cleared, with Troy as your one point of contact.
Closing and funding
Signing is scheduled around you. Troy coordinates escrow so the loan funds on the date you planned.
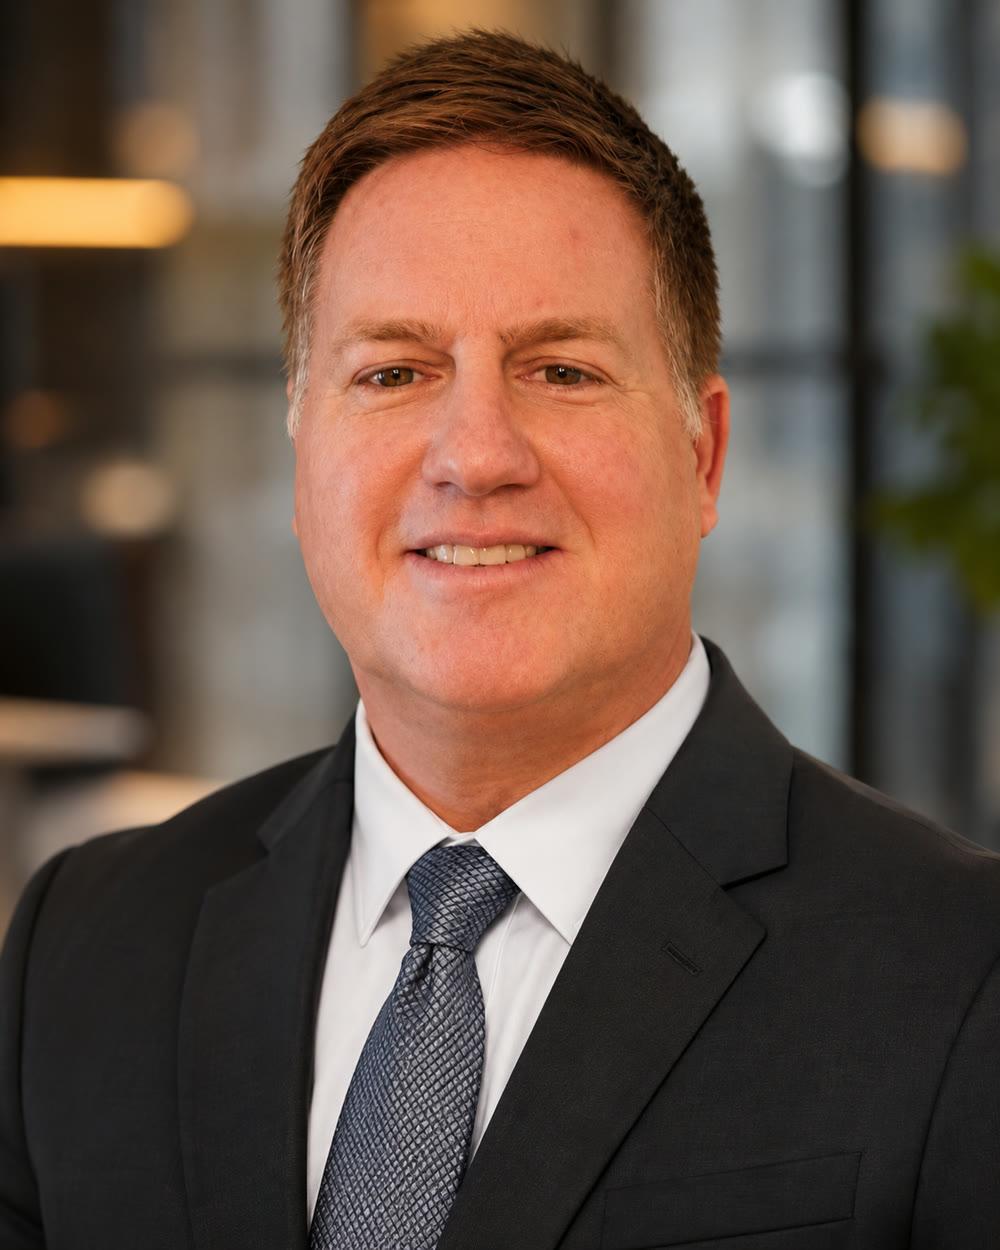
Troy reads this file himself.
The person who quotes your loan is the person who closes it. No call center, no processor you never meet, no hand-off between the first call and funding.
- Licensed
- CA DRE Broker 01403185 · since 2004
- NMLS
- 355886 company · 271117 individual
- Office
- 2271 Ohio Avenue, Signal Hill, CA 90755
- Lends in
- California
Questions people ask
General answers. The answer for your file comes from a conversation with Troy, not from a web page.
What is the difference between a commercial loan and a DSCR loan?
A DSCR loan is a residential investor loan for one-to-four-unit rentals. Buildings of five units or more, mixed-use and business property are commercial and go to commercial lenders with their own underwriting.
Do you need my tax returns?
It depends on the lender and the loan. The property's income is the main consideration, and Troy tells you exactly what a given lender asks for before you apply.
How long does a commercial loan take?
Longer than a home loan, mostly because of the third-party reports. Troy gives you a timeline for your property once the lender is chosen.
Do you lend outside California?
No. Troy is licensed to originate loans in California only.
Related programs
Often considered alongside this one. Troy prices the alternatives so you can see them side by side.
DSCR investor
Investor financing qualified on the property's rental income rather than personal tax returns.
Bank statement
Self-employed income documented with 12 or 24 months of deposits instead of tax returns.
Refinance
Lower the payment, shorten the term or take cash out, with the before-and-after on the table before you decide.
Home purchase
Conventional, FHA, VA, jumbo and down-payment assistance, with a pre-approval that has been underwritten before the letter goes out.
Talk it through with Troy.
No obligation and no credit pull on the first call. Tell him what you’re trying to do and he’ll tell you whether commercial financing is the right tool, and what it would cost.